Website design for SACCOs and microfinance institutions
Members want the interest rate and the requirements before they walk in. Publishing both is what separates you from a money lender.
Typical for a saccos and microfinance website
From deposit to live, depending on size
We write the pages, you check them
Domain and hosting in your name
People are careful with money institutions, and rightly so. Somebody considering joining a SACCO or taking a loan wants to know the rate, the repayment period, what security is needed and whether the institution is registered. Vagueness reads as a trap.
We build SACCO and microfinance sites on transparency: every product with its rate and requirements, your registration and supervision clearly stated, and a membership or loan enquiry that starts the process properly.
A SACCO is asking people to hand over savings, which makes trust the entire product. Prospective members want to know who runs it, whether it is properly registered, whether accounts are audited, and what happens to their money if something goes wrong. Publishing the registration, the board, the supervisory committee and recent audited accounts is not bureaucratic dullness - it is the single most persuasive thing you can put on the site, particularly given how many people have been burnt by informal schemes.
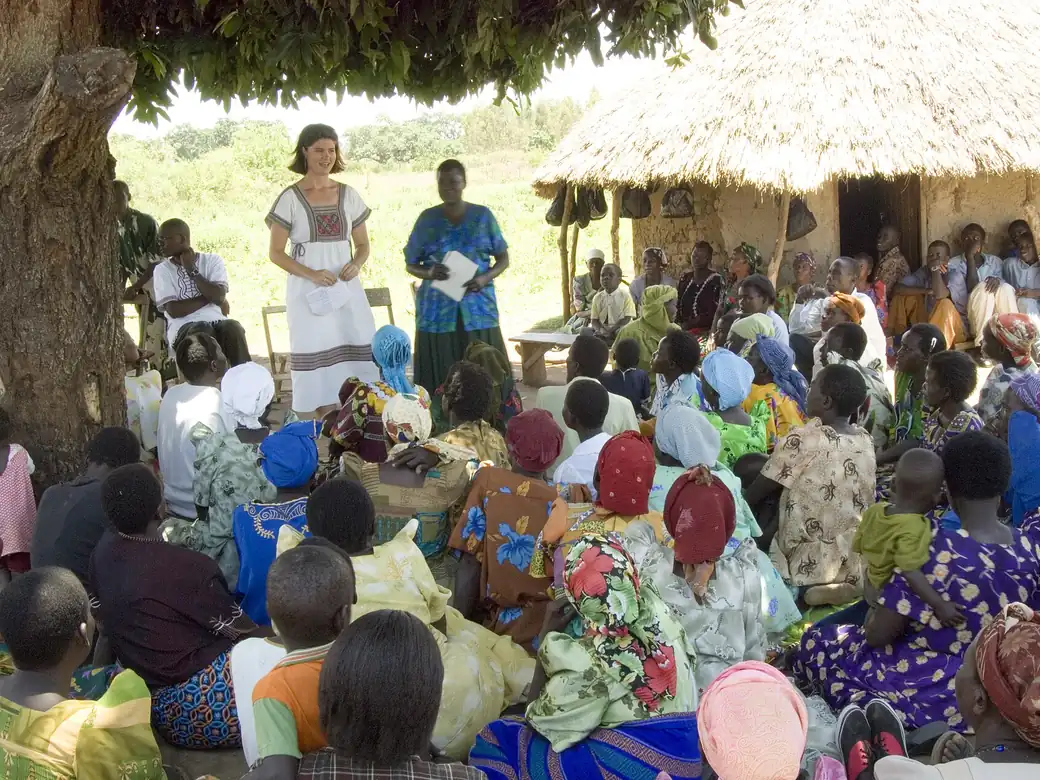
Most SACCOs grow through groups rather than individuals - a staff association, a boda stage, a market section, a teachers' union branch, a church group. That is a different conversation from recruiting one member at a time, and it deserves its own page: what you need to onboard a group, how payroll or stage deductions work, what the group gets that an individual does not, and who comes to address a meeting. Add a simple loan calculator so a prospective member can see the repayment before asking anybody. Those two pages will do more for membership than a hundred posts about teamwork.
The mistake we see most often
The trust gap is the whole battle. Uganda has had enough collapsed schemes that members check carefully. Your registration number, your board, your audited accounts and your physical office do more for conversion than any design choice.
What a saccos and microfinance website needs
- Loan products with interest rates, terms and security required
- Savings products and what they earn
- Membership requirements, joining fee and share capital
- Registration and regulatory details - registration number, supervision
- Board, management and, where you publish them, audited accounts
- Branch locations, hours and a loan or membership enquiry form
Included as standard
Every site we build leaves our hands with all of this. None of it is an extra.
Built for phones first
Nearly all your visitors will arrive on a phone, often on mobile data. That is where we design and where we test.
WhatsApp and call on every page
A tap to call and a tap to chat, always visible. Most Ugandan enquiries arrive this way, not through forms.
Google Business Profile
Set up and verified so you appear on Google Maps with your hours, photos and phone number.
What it costs
A saccos and microfinance website usually lands in the Business package, from UGX 750,000. Half to start, half at launch.
Domain and hosting are separate and paid to the hosting company - roughly UGX 150,000 to 300,000 for the first year, registered in your name.
Questions from saccos and microfinance
Must we publish our interest rates?
You should. Borrowers compare, and an institution that will not state a rate looks like it has something to hide. Publish the rate and the basis - reducing balance or flat - because that difference is what borrowers most often misunderstand.
Can members check balances online?
A member portal is a much bigger, more sensitive build than a website and it needs to connect to your core system securely. Start with an informational site plus loan enquiries. Add a portal when the member numbers justify the cost and the security work.
How do we look credible next to the banks?
By being specific where banks are vague. Real branch photos, named management, your registration number, your actual rates and the community you serve. Members choose a SACCO precisely because it is not a bank, so show the people.
How do we show members their savings are safe?
By publishing the things an unsafe scheme cannot. Your registration under the Cooperative Societies Act with the number, your regulator, the board and supervisory committee with names and photographs, and audited financial statements for recent years as downloads. Explain how loans are approved and by whom, so members can see it is not one person's discretion. Publish the dates of your annual general meetings and what was resolved. None of this is exciting, and that is rather the point - the fraudulent outfits compete on promised returns, and you compete on being verifiable.
Should we publish our loan requirements and the forms?
Yes, all of it. Members waste days coming to the office to find out what is needed, and staff waste the same days explaining. Publish the requirements for each loan product - guarantors, savings history, documents, security where it applies - and how long approval usually takes from a complete application. Put the forms up as downloads and say where to submit them. Being specific about the time it takes is the part that builds trust: a SACCO that says approval takes seven working days and then does it in seven is trusted far more than one that promises immediately and takes three weeks.
Related
Accountants and auditors
Small businesses search for URA deadlines and company registration all year. Answer those and you meet your next retainer client.
Read moreInsurance brokers
Motor third party, medical, property. People search for the cover, not the broker. Give each product its own page.
Read moreFarms and agribusiness
Buyers and exporters search for supply. If your capacity is not online, you are not in the conversation.
Read moreReady to talk about your saccos and microfinance website?
One WhatsApp message with what your business does is enough. We reply with what your site needs, what it costs and how long it takes.